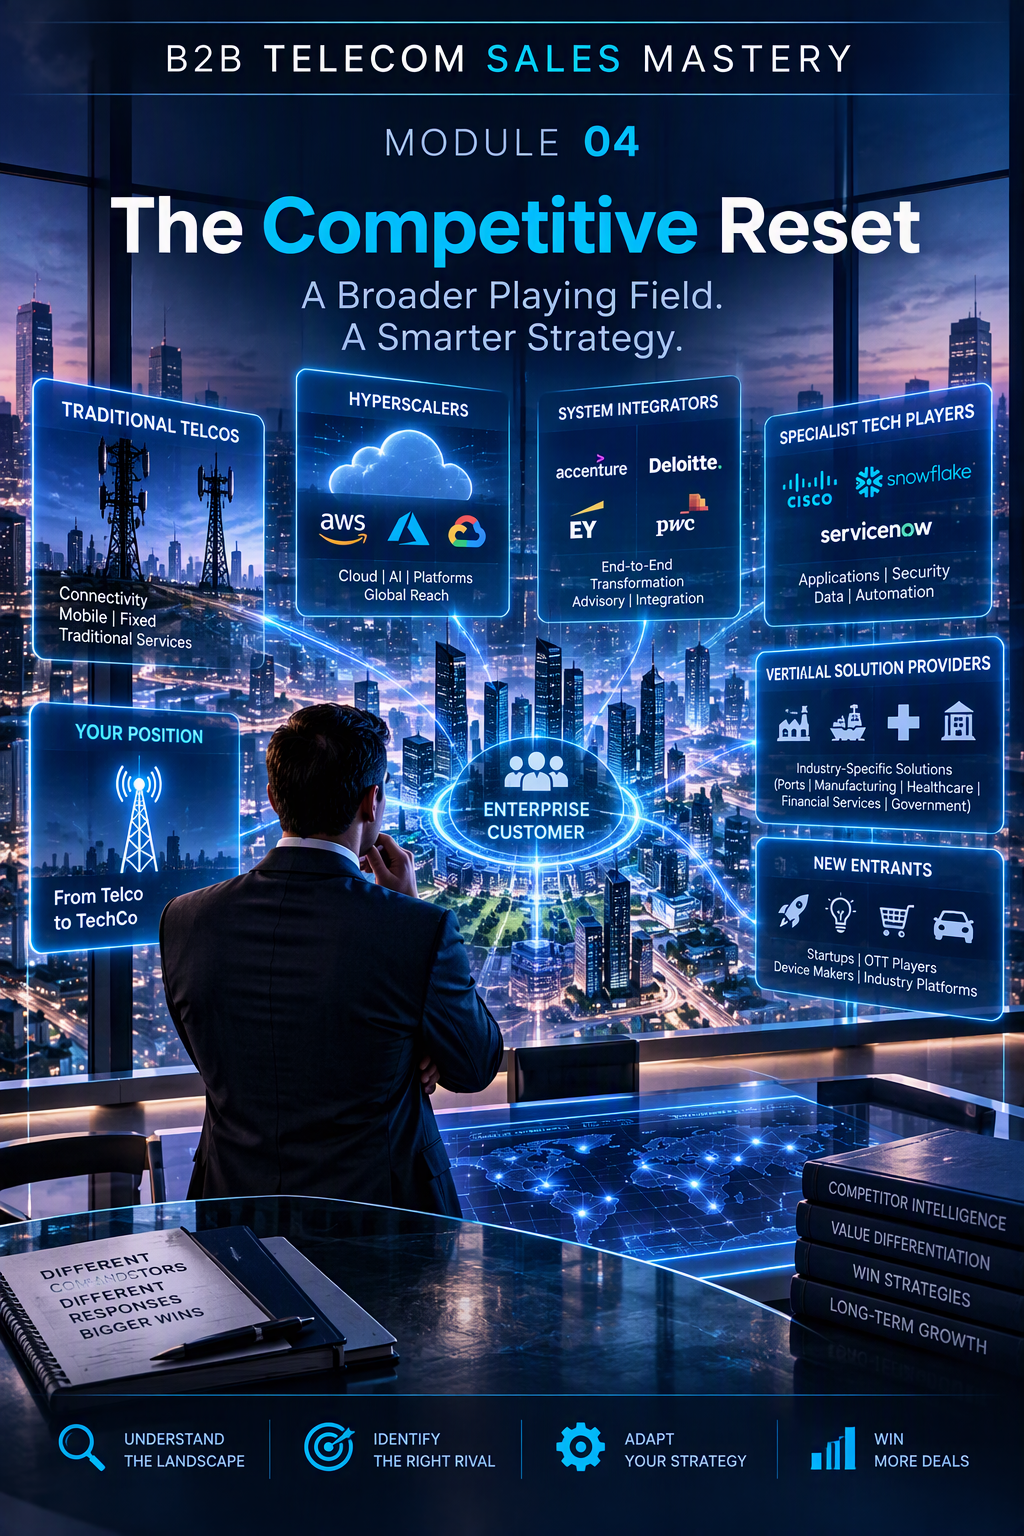
For most of telecom’s history, the competitive set for an enterprise deal was simple: the operator across the street. Module 1 established why that’s no longer true — 35% of operator revenue now sits in a $400 billion beyond-core market, and that market has real competitors who were never in the connectivity business at all. This module is about recognizing which kind of rival is actually in a given deal, because the right response is different for each.
Losing to another telco is a pricing problem. Losing to a hyperscaler is a positioning problem. Treating them the same loses both.
Four competitor types, and how each one actually wins
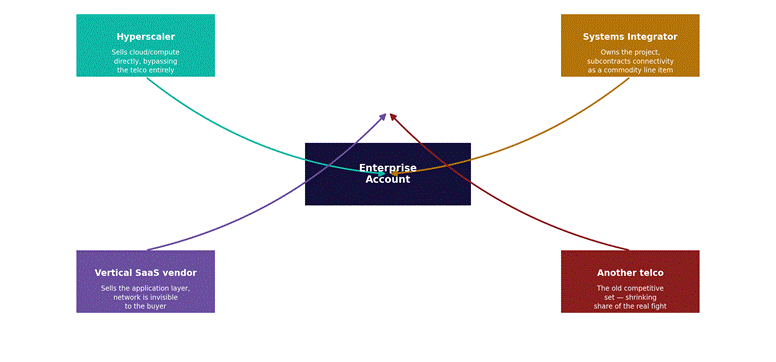
Figure 1. Four distinct competitor types now compete for the same enterprise budget, each with a different mechanism.
| Competitor | How they win | How to recognize they’re in the deal |
| Hyperscaler | Sells cloud/compute directly to the customer’s technical team, bypassing procurement’s usual telecom vendor list entirely | The customer’s IT team already has an existing cloud relationship; the RFP scope includes compute/storage the telco doesn’t naturally own |
| Systems integrator | Owns the overall project and treats connectivity as a subcontracted commodity line item inside a bigger deal | The opportunity surfaces through a project RFP, not a direct telecom procurement process; connectivity is one line among many |
| Vertical SaaS vendor | Sells the application layer directly to a business unit; the network becomes invisible infrastructure underneath | The buyer is a business-unit leader, not IT; the pitch they’re hearing is about the application outcome, not the network |
| Another telco | Competes on price, SLA, and coverage within the traditional connectivity RFP process | The opportunity looks and moves like a classic telecom RFP, timeline and all |
Why this matters for how a deal gets worked
The practical risk isn’t losing to a hyperscaler or SI in a head-to-head bid — it’s not knowing they’re in the deal at all, because they entered through a door the account team wasn’t watching. A hyperscaler relationship starts in the customer’s engineering team, often years before procurement hears about it. Module 3‘s shadow-infrastructure signal is the specific mechanism for catching this early — traffic patterns revealing a cloud relationship nobody on the account team knew existed.
The GCC market makes this concrete rather than theoretical: global cloud providers are already live or announced in every major GCC market, meaning the hyperscaler competitor isn’t a future risk to plan for — it’s already in-region, already sellable to the same accounts, right now.
Response strategy by competitor type
- Against a hyperscaler: don’t compete on being a cloud provider — compete on being the connectivity, compliance, and in-region presence layer the hyperscaler needs a local partner for. The pitch is integration, not substitution.
- Against a systems integrator: get into the project before the RFP is scoped. Once connectivity is a subcontracted line item inside someone else’s project, the deal is being priced as a commodity by definition — the only way out is being positioned as the SI’s partner, not their vendor.
- Against a vertical SaaS vendor: reach the business-unit buyer directly with an outcome-framed pitch, using the same language Module 1’s self-assessment table describes as the TechCo column — because that’s exactly the register the SaaS vendor is already using.
- Against another telco: this is the one case where traditional competitive selling — price, SLA, coverage — still works largely as it always has.
What comes next
Module 5 moves from recognizing competitors to building a structured account plan — including a whitespace-mapping template for identifying exactly where each competitor type is likely already present in an account, before the deal surfaces.
Think of your current pipeline: how many open opportunities have you mapped against all four competitor types, versus just checking for another telco?